
Capital Markets Playbook | Q4 2026

2026 Q3 Summary
- Returns were mixed across global equity markets in the third quarter of 2026.
- U.S. large caps outperformed domestically while international small caps outperformed all equity asset classes.
- U.S. small cap stocks underperformed all other equity asset classes in the quarter (-7.2%).
- In what is proving to be a volatile year for commodities, primarily due to changes in energy prices, commodities were the best-performing “risky” asset in Q3.
- Broad-based volatility in yields resulted in declines across most fixed income asset classes in the quarter, leading to losses for the year in most categories.
- Global bonds experienced their worst quarter in nearly two years. The U.S. Aggregate Bond Index declined 3.5% in Q3.
- Declines occurred in nearly every fixed income asset class. Emerging market debt was the only fixed income asset class with positive performance in the quarter. EM debt has benefited from the U.S. dollar depreciation and central bank actions.
2026 Q3: In Review
- U.S. Macroeconomic Review
- Economic Growth
- The U.S. economy expanded by 2.2% in the second quarter of 2026, primarily driven by ongoing strength from the consumer and investment activity.
- Economic growth is expected to remain near current levels through the end of 2027.
- Consumer Spending
- Consumer spending remains strong and accelerated in the quarter despite expectations for deceleration due to headwinds from sustained higher energy prices.
- Unemployment
- Unemployment, currently at 4.2%, has continued to decline throughout the year. A tight labor market helped strengthen the Federal Reserve’s case to hike rates at its September meeting.
- Inflation
- The Fed’s preferred measure of inflation, the Personal Consumption Expenditures (PCE) Index, has remained stubbornly high.
- Core PCE remains approximately 100 bps above the Fed’s target rate of 2%.
- Interest Rates and Monetary Policy
- The Fed raised its short-term policy rate by 25 bps to 3.75-4.0% in September. This was the first change to the overnight rate in 2026 and the first rate hike since 2023.
- The Fed hinted that the Committee may hike rates at least once more before the end of the year due to persistent inflation.
- Economic Growth
- Equity Market Review
- Broad-based equity markets finished the quarter up +1%.
- Growth stocks experienced elevated volatility in the quarter, as investors showed concern over the large capital expenditures on data center buildouts and near-term return on investment.
- While U.S. large caps significantly outperformed U.S. small caps, emerging markets and international large caps, international small caps ultimately delivered the highest return among major equity asset classes.
- Even with most equity asset classes up over 10% on the year, forward valuations have largely declined, as expected future earnings have outpaced price return.
- Broad-based equity markets finished the quarter up +1%.
- Fixed Income Market Review
- Treasury yields moved meaningfully higher in Q3 2026.
- The two-year yield increased +74 bps during the quarter, while the 10-year yield increased +85 bps.
- Longer-term yields (i.e., the 10-year yield and 30-year yield) ended the quarter at multi-decade highs.
- Higher rates were driven by higher energy prices, high inflation and ongoing strength in consumer spending.
- Treasury yields moved meaningfully higher in Q3 2026.
Risks to the “Expected Case” in 2026
- Elevated Asset Class Valuations
- Equities and real estate make up a significant percentage of households’ total net worth and have likely helped keep consumer spending levels high. Equities and homes had significant price gains for the past five years. A reduction in asset values would likely lead to slower spending growth, weaker labor markets and slower economic growth.
- Unexpected Labor Market Weakness
- An unexpected softening of the labor market would create headwinds to consumer spending and lead to slower economic growth.
- Unexpected labor market weakness may create a more acute “affordability crisis” for low- and middle-income households.
- An Unexpected Pickup in Inflation
- Rising energy prices have historically pressured headline inflation. If the conflict in the Middle East escalates further or if oil supply remains disrupted for an extended period, inflation expectations may rise further or remain elevated for longer.
- Mounting Concerns Over U.S. Debt and Deficits
- Mounting concerns over U.S. debt and deficits could lead to higher long-term interest rates.
- Unexpected Geopolitical Issues and Midterm Elections
- Unexpected geopolitical events can significantly influence financial markets over short periods of time.
- Uncertainty associated with U.S. foreign policy could have negative impacts on market volatility, global trade flows and the global economy.
- The lead-up to midterm elections in the United States could present heightened headline risks, resulting in increased volatility over the short term.
- The “Unknown Unknowns”
- The most threatening risks to the “expected case” are always those that catch markets by surprise. The most recent examples of exogenous shocks are the emergence of COVID-19 in late 2019/early 2020 and the tariff announcements in early 2025.
2026 Expectations: Economic Growth
- U.S. economic growth is expected to continue near current levels through 2027.
- Unemployment is expected to remain stable and consumer spending is expected to remain strong through the rest of 2026.
- While the probability of an economic contraction in the United States may be higher today due to energy-related supply disruptions overseas, the expectation for continued strength in consumer spending implies a low recession risk in the quarters ahead.
- Scenarios
- Best Case
- Economic activity in the United States will come in slightly above its long-term trend rate over the next two years.
- Expected Case
- Economic activity in the United States is near its long-term growth rate over the next two years.
- Worst Case
- Economic activity will fall below its long-term trend rate over the next two years. An economic recession is not expected.
- Best Case
2026 Expectations: Unemployment
- Unemployment in the United States has declined from the start of the year and is now at 4.2%, well below its long-term average.
- Unemployment is expected to increase slightly by the end of the year.
- Few expect unemployment to increase meaningfully through 2027.
- Scenarios
- Best Case
- Unemployment declines from its current level and remains near historical lows over the next two years.
- Expected Case
- Unemployment remains near current levels of 4.2% for the next two years as the U.S. economy continues to grow and remains well below its longer-term trend rate.
- Worst Case
- Unemployment rises slightly through the end of 2027 as a result of meaningfully slower economic growth.
- Best Case
2026 Expectations: Inflation
- Despite Core CPI moving higher earlier in the year as energy supply chains were disrupted, CPI levels have once again started to retreat.
- Inflation levels remain above the Fed’s long-term target.
- Inflation levels may have peaked. With crude oil exports showing signs of recovering toward pre-war levels, inflation levels are expected to ease going forward.
- Scenarios
- Best Case
- Inflation declines but remains above the Fed’s long-term inflation target of 2% through 2027.
- Expected Case
- Inflation continues to moderate very slowly and is about 50 bps higher than the Fed’s long-term inflation target by the end of 2027.
- Worst Case
- Inflation continues to be sticky throughout the aggregate economy and is approximately 1.0% higher than the Fed’s long-term inflation target through the end of next year.
- Best Case
2026 in Focus: Geopolitical Implications
- The tentative de-escalation seen in late Q2 proved short-lived. Middle East supply chain friction, depleted reserves and elevated shipping costs drove crude oil prices up sharply during the third quarter.
- The oil futures curve remains in steep backwardation, indicating that markets are pricing in immediate supply tightness rather than a permanent long-term price shift.
- Rising energy costs continue to exert upside pressure on broad inflation figures, serving as a primary driver behind the Federal Reserve's 25 bps rate hike in Q3 and reinforcing a "higher for longer" policy stance.
- The situation overseas remains fragile, and energy prices will remain elevated until supply channels return to pre-conflict levels. Security prices may fluctuate with developing headlines on any progress in talks between the United States and Iran.
- Takeaway
- Energy price volatility continues to act as a primary catalyst for inflation headlines and short-term market swings. Investors should maintain a disciplined, multi-asset allocation rather than overreacting to geopolitical commodity spikes.
2026 in Focus: AI a Key Driver of Performance
- A disproportionate share of equity market gains, especially in the United States, have been driven by companies most directly exposed to AI over the past couple of years.
- Market gains have been concentrated in the largest companies by market cap. The cap-weighted S&P 500 has outpaced the equal-weighted index by approximately 3% YTD, as a handful of large companies are doing most of the heavy lifting for the broader market.
- Major AI enablers continue to deliver strong earnings results and profit growth that back up their outsized index weights.
- Takeaway
- Market gains reflect the immense earnings power of the major AI players. While their strong profit growth supports these valuations, holding a broader, diversified portfolio protects clients from over-reliance on a concentrated group of stocks.
2026 in Focus: Hyperscalers Driving Investment
- As AI investment continues to surge, the market has been cautious to reward several of the largest spenders, as it waits for more proof of returns on their investment.
- Hyperscalers have historically been some of the more profitable cash-generating businesses and have been using the cash they bring in from their core businesses to expand on AI infrastructure.
- Consensus estimates imply negative free cash flow through 2027 before rebounding sharply in 2028 and beyond.
- AI capital expenditures are expected to peak around 2028. As AI applications become more integrated into enterprise workflows and consumer products, revenue and free cash flow are expected to rebound.
- Takeaways
- With growing demand for AI, strong incentives and the ability to spend on the infrastructure, continued capex investment looks set to continue as investors wait on signs of improved profitability.
- Proof of successful monetization of AI investment through recurring cash-generating engines is essential to renewing investor confidence.
2026 in Focus: U.S. Midterm Elections
- Midterm election years have historically been associated with higher volatility as uncertainty builds.
- Market volatility tends to grow as Election Day nears but often stabilizes as it passes with investors gaining greater clarity about the future.
- Stock market returns are primarily driven by factors beyond government policy.
- Market returns have historically been strong over the following one-year period after a midterm election.
- Average one-year returns after midterm elections: 15.4%
- Average one-year return across all years: 7.8%
- Takeaways
- Midterm election years often bring heightened volatility that subsides once the results are known.
- The stock market has performed well in various political environments, as it is shaped more by economic growth and corporate earnings than politics.
Expectations Historically Elevated & Still Climbing
- Current earnings expectations are high relative to history.
- Since 1960, annual S&P 500 earnings growth has averaged roughly 8%, while current calendar-year expectations are near 32%.
- Earnings growth above 20-25% has been uncommon outside unusual periods, such as recessions, tax-related distortions or sharp cyclical rebounds.
- Analyst revisions have become more constructive, but that also raises the bar for performance. The risk of earnings sustaining these growth levels is elevated.
- Takeaway
- Due to elevated expectations, markets may become more sensitive to signs that earnings growth is slowing or revisions are beginning to fade.
Fair Valuations & Strong Earnings Anchor Equity Outlook
- Broad market valuations appear fairly valued as the S&P 500 index sits exactly at its 10-year historical average valuation. The improvement in valuation has been propelled by genuine corporate earnings growth rather than speculative multiple expansion.
- Analysts are actively raising earnings forecasts for more S&P 500 companies than they are cutting, showing that corporate profit strength is widespread across the index.
- Takeaway
- Market performance and earnings expansion remain anchored by resilient corporate profit margins and capital efficiency. While macroeconomic headwinds and rate noise persist, persistent profit growth provides a durable foundation for long-term investors.
Relative Valuations: U.S. Large Cap Comparison
- Over the last quarter, fundamental valuation metrics haven’t shifted materially. U.S. equities remain “expensive” relative to international equities.
- Emerging market equities have experienced significant outperformance over the last year, but that performance has moderated over the last quarter. Even with the tempering of EM outperformance, U.S. large cap stocks still appear “more expensive” than emerging market equities on a fundamental basis.
- Takeaway
- Diversification outside the U.S. is prudent, and we recommend investors continue to have an allocation to international equity and EM equity.

Relative Valuations: Growth vs. Value Comparison
- Volatility was elevated in the third quarter. U.S. growth stocks maintained their upward trajectory as fundamental valuations remained slightly below their 10-year median. Value stocks outperformed growth in the quarter and year-to-date periods.
- On a fundamental valuation basis, international value stocks remain “more expensive” than international growth stocks.
- International value stocks maintained strong performance through the third quarter, as investors prioritized resilient corporate earnings and higher dividend yields.
- Takeaway
- Diversification between growth and value stocks is recommended.

Fixed Income: Treasuries
- In recent months, U.S. Treasury yields have surged as investors weighed elevated energy prices, sticky inflation, concerns over rising U.S. national debt, persistent budget deficits and the resilience of the U.S. economy and consumer spending.
- The yield curve is no longer inverted at the short end of the curve, as short-term yields moved higher on Federal Reserve actions.
- Takeaways
- Intermediate and long-term U.S. Treasury yields are currently at or near multi-decade highs.
- A return to the ultra-low yield environment seen for much of the past 18 years is unlikely to occur anytime soon.
- Investors that have a lower ability or willingness to take risk should consider adding to fixed income in their investment portfolios.
Fixed Income Yields vs. Historical Ranges
- Fixed income yields have increased substantially in recent quarters and are currently near multi-decade highs.
- Fixed income assets currently produce income at levels not seen since before the Global Financial Crisis.
- Yields at current levels signal the possibility for strong forward returns across nearly all fixed income asset classes.
- Takeaway
- In addition to producing income, fixed income assets provide investors with diversification that is beneficial during periods of equity market volatility. This may provide further opportunity for strong forward return expectations in a period when future equity earnings growth is expected to decline.
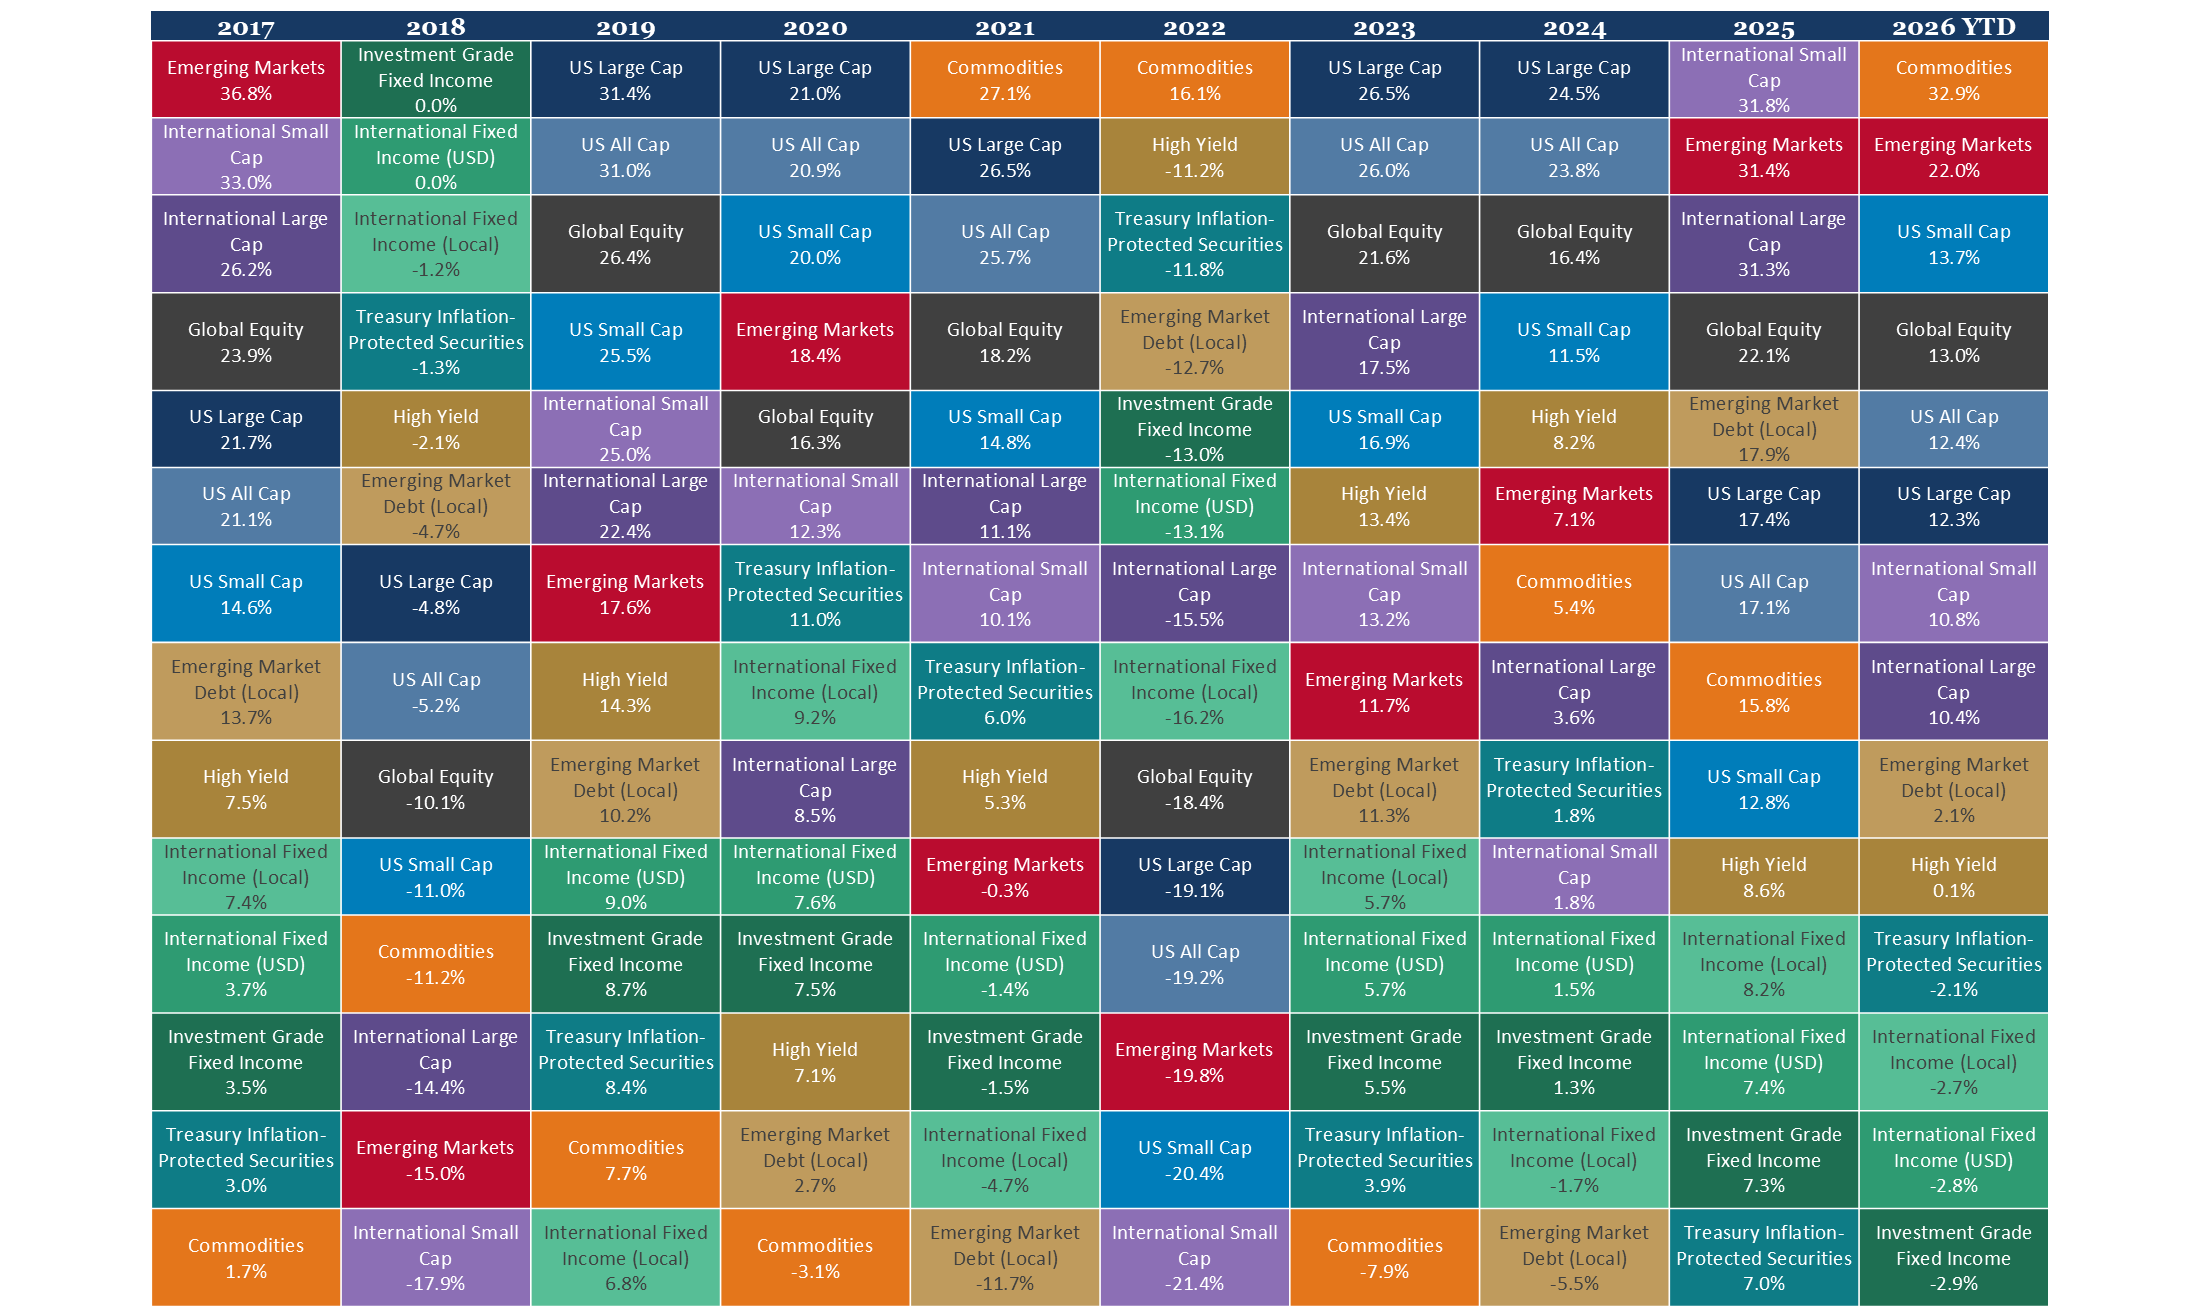
Asset Class Performance – Annually
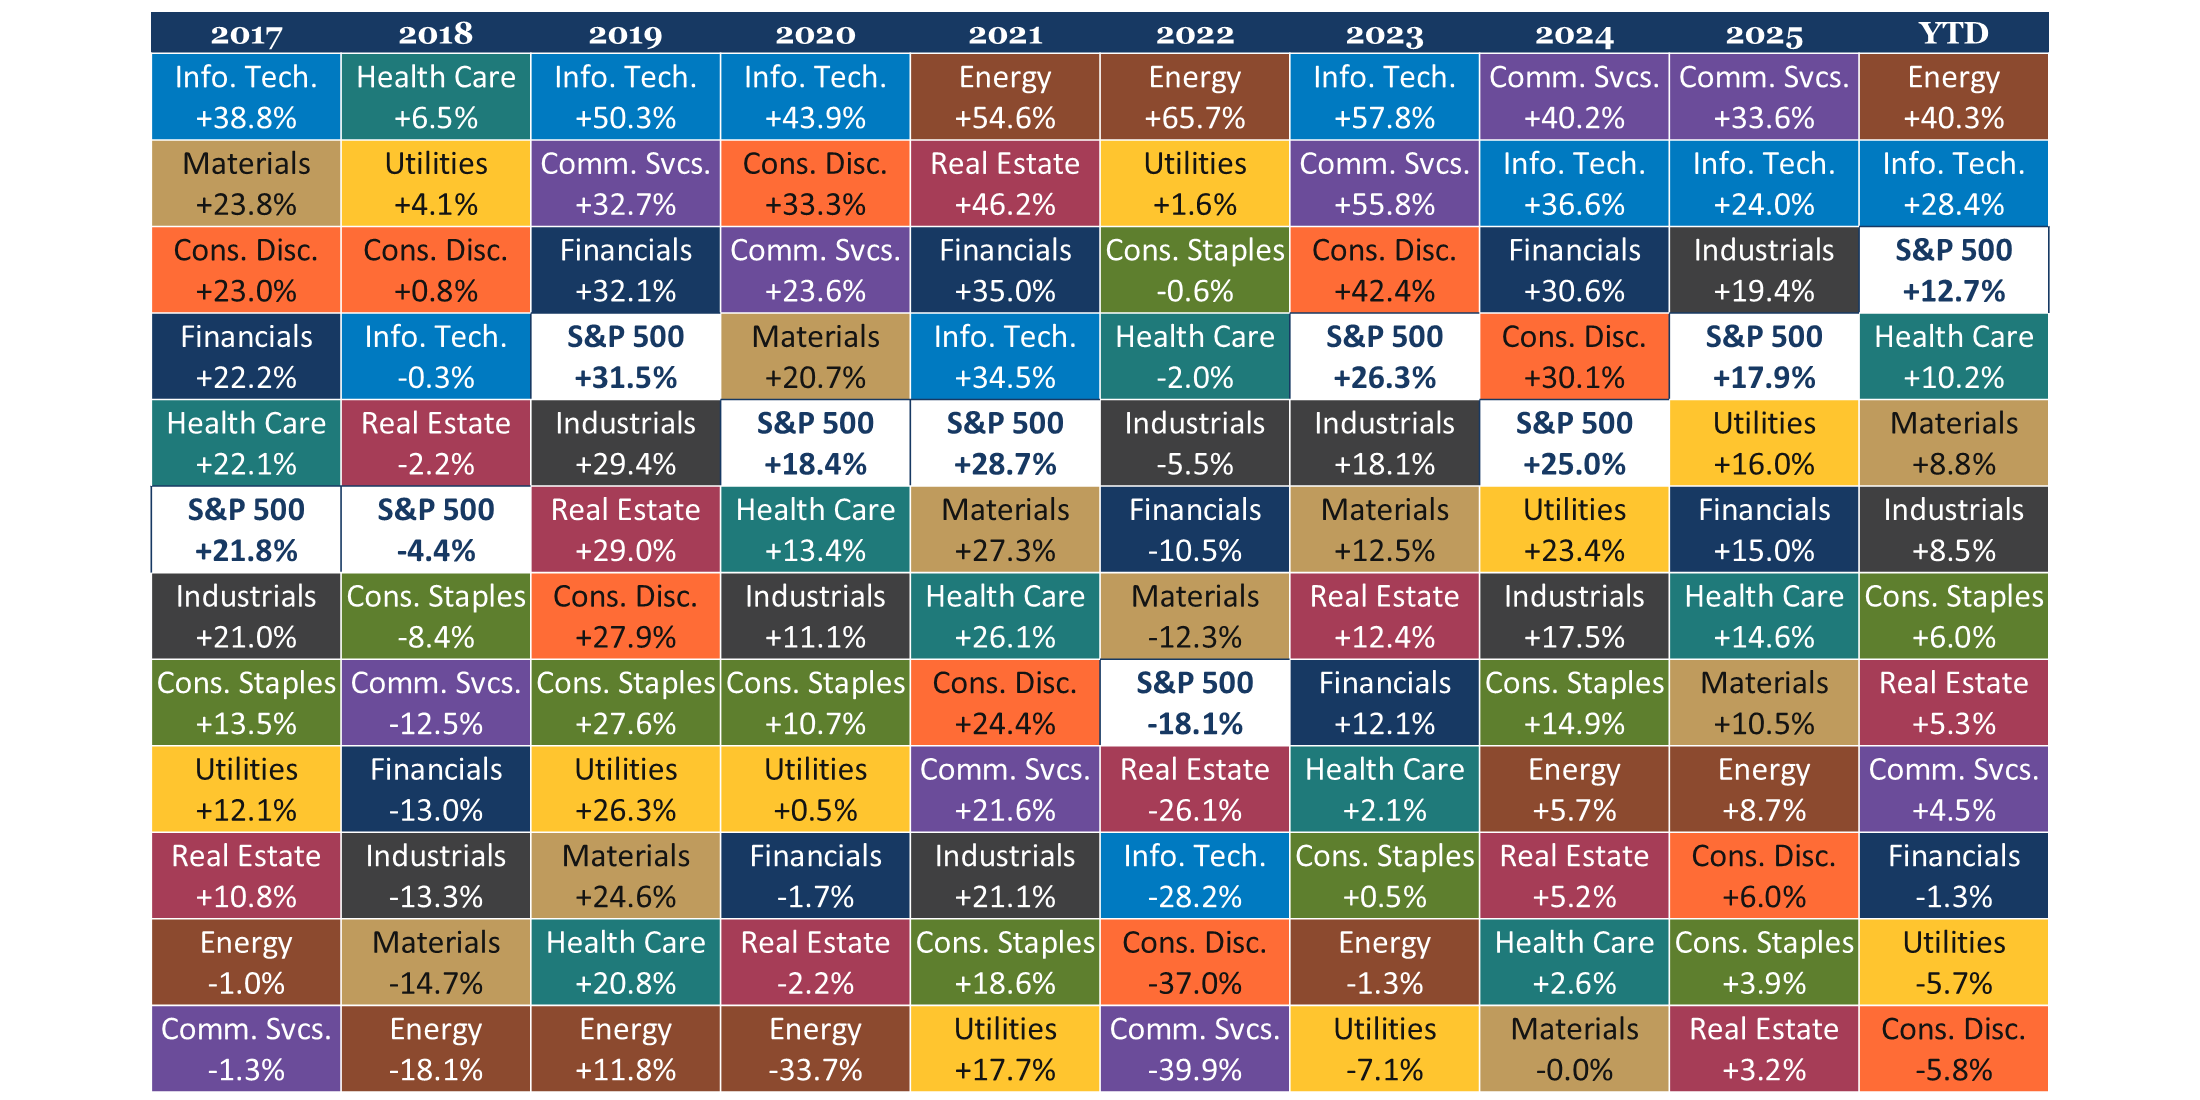
Sector Performance – Annually
Equity Market Volatility
- The chart illustrates annual S&P 500 performance since 1980 (shown in columns above) and the intra-year declines during each year (shown by the red dots).
- Ex: In 2020, the S&P 500 experienced an intra-year decline of -34% before finishing up 16% for the year.
- Over the past 46 years, the S&P 500 has experienced an average intra-year decline of 14%. Despite that, the S&P 500 had positive annual performance in 34 of the last 46 years.
- Takeaway
- As painful as market volatility can be, equity market selloffs are normal, and investors are rewarded for patience.
Playbook Summary
- The table above indicates where each major investment asset class falls on the distribution of attractiveness (from low to high). This table is meant to provide a standardized and comparable view of the level of opportunity in each asset class category.
- In subsequent quarters, we will discuss any movement along the scale for each asset class and the driving forces behind the change in outlook.
Disclosures
Investment services offered by Enterprise Bank & Trust are not deposits, obligations, or guaranteed by the bank or its affiliates. The information provided represents the opinions of Enterprise Bank & Trust and is not intended to forecast future events or guarantee future results. Past performance does not guarantee future returns. This information is for educational purposes only. Investors should consult with their investment professionals for advice concerning their particular situation.
Investments are: *Not FDIC insured *May lose value *Not financial institution guaranteed *Not a deposit *Not insured by any federal government agency.

